Overview
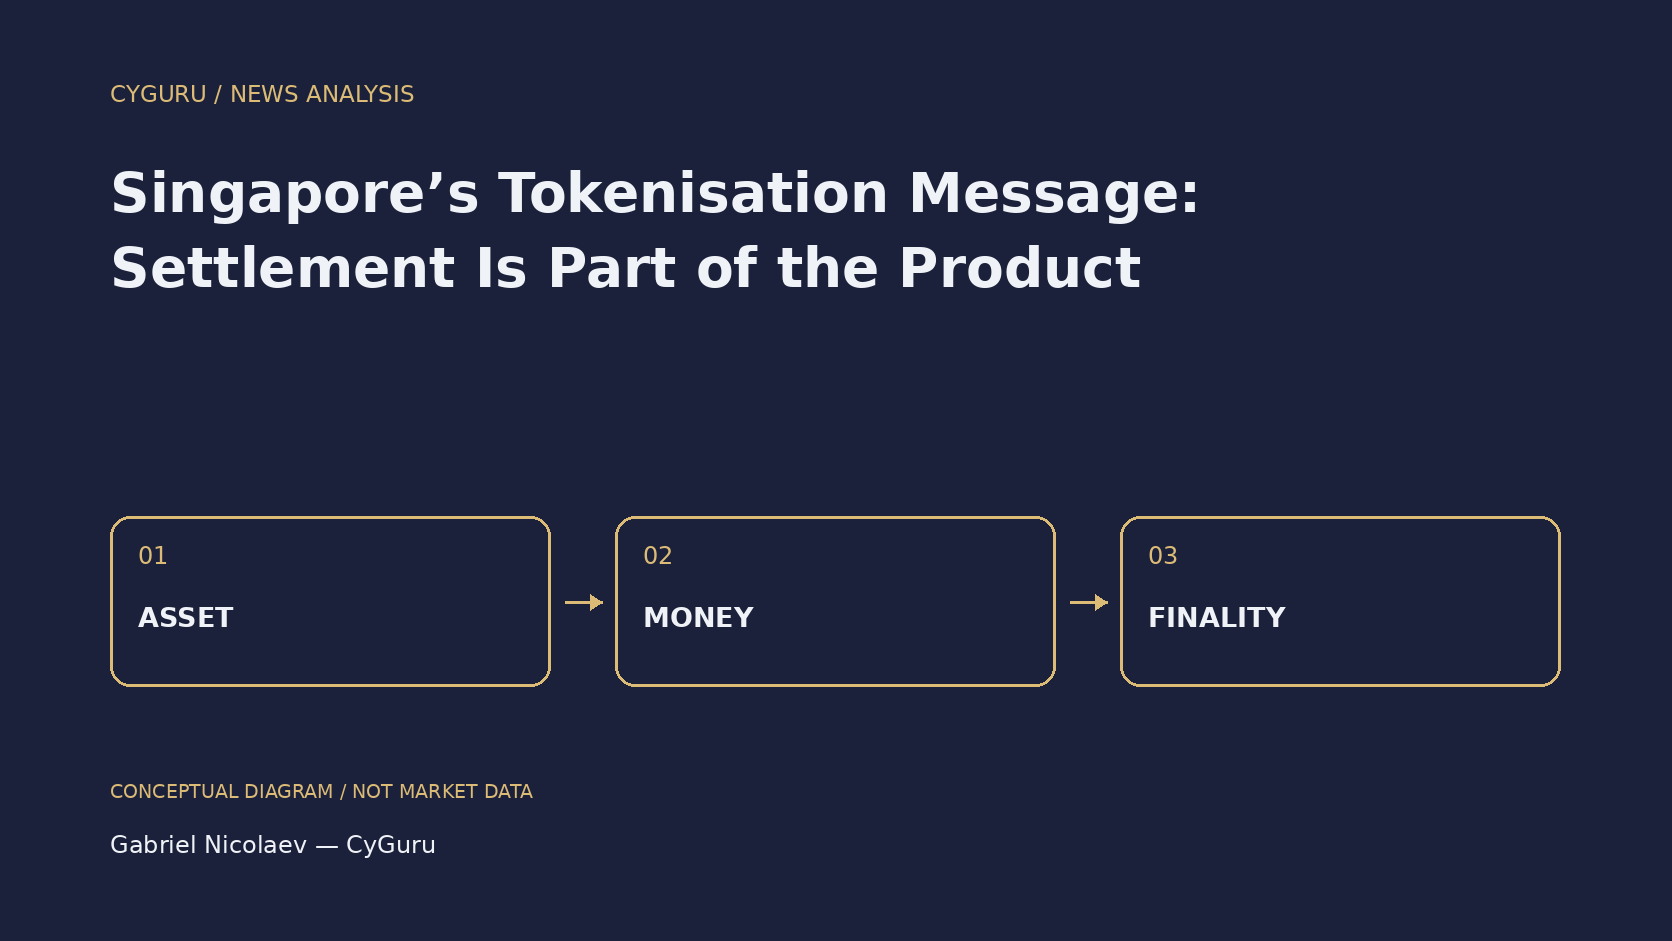
Published 5 November 2026. A 19 October speech on digital finance, published by the BIS, places trusted settlement alongside tokenisation. The useful question for readers is not only whether an asset can be represented on a ledger, but what money completes the transaction and under what conditions settlement becomes final.
What the speech describes
The speech discusses interoperability, legal clarity and standards as foundations for adoption. It describes tokenised bank deposits, regulated stablecoins and central-bank digital currency as potentially serving different needs. It also discusses Singapore’s work on wholesale central-bank digital currency and tokenised MAS Bills. These are statements about infrastructure and policy work, not evidence that every tokenised product already shares one settlement arrangement.
Why the distinction is practical
Consider an illustrative transaction that transfers a security successfully but leaves payment uncertain. Technical movement of one leg has not answered the whole commercial question. The editorial implication is to examine the asset, settlement money, legal terms and exception process together. A fast demonstration can show that software executed; it cannot alone establish that all legal and operational questions have been resolved.
What to watch
Follow the specific infrastructure, participation conditions and official implementation documents. Avoid turning a speech about trusted digital finance into an endorsement of a privately marketed token. This report does not claim a new consumer investment opportunity or forecast returns. The companion bridge guide examines added dependencies between networks; the same habit of mapping the full chain of responsibility is useful when evaluating a tokenised settlement proposal.
Go deeper on CryptoGov
Sources & verification
Researched and published by CryptoGov Editorial Desk. This article contains editorial analysis; assessments are distinguished from reported facts.